
Unfunded Revocable Trust
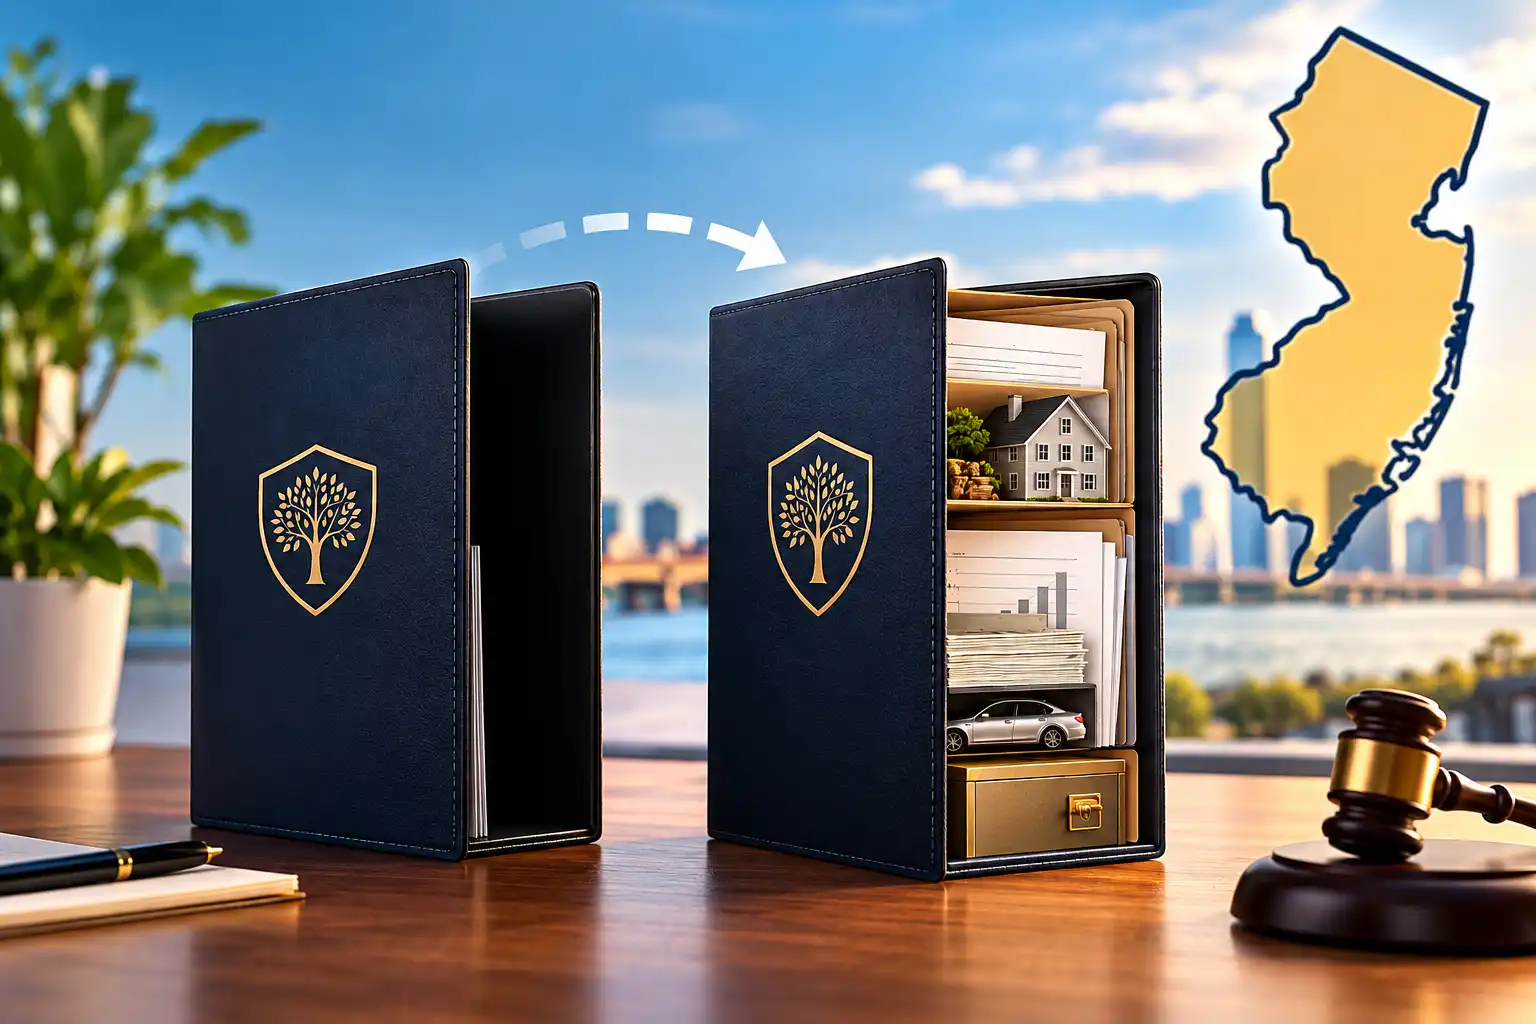
Of all the gaps I see in estate planning when families bring me their existing documents, this is the most common one, and the most damaging. A family invested time and money to create a revocable living trust. The documents sit in a folder, nicely bound, with their names on them. The family believes their estate plan is in place.
But the trust isn't funded. And an unfunded trust does nothing.
Before I get into the specifics, one note. Not every family needs a revocable trust. For many New Jersey families, a well-drafted will combined with properly structured beneficiary designations accomplishes everything they need. Trusts are the right tool when there are specific reasons to use one (out-of-state property, significant privacy concerns, a desire to avoid New Jersey's probate process, complex family structures, incapacity planning considerations). If your family already has a trust, this piece is for you. If you're wondering whether you should have one, that's a different conversation and the answer depends on your specific situation.
For families who do have a trust, here's what matters.
What funding actually means
A trust is a legal container. Creating the trust document is the work of building the container. Funding the trust is the work of actually putting your assets into it.
In practice, funding looks different depending on the asset:
Real estate: The deed to your home has to be re-recorded with the trust as the owner. Your name as an individual comes off; the trust's name goes on.
Bank and brokerage accounts: The account itself has to be retitled so the trust is the owner. Many families open new accounts in the trust's name and transfer the balance; others work with their bank to retitle the existing account.
Business interests: LLC membership interests, S-corp stock, partnership interests all have to be formally transferred to the trust through the business's operating agreement or shareholder documents.
Life insurance and retirement accounts: These usually stay in the individual's name but have the trust named as a beneficiary (though for retirement accounts, naming a trust as beneficiary has significant tax implications that need careful analysis before doing it).
Each of these steps requires separate paperwork, separate filings, and in some cases separate fees. Many families complete some but not all of these steps and assume the trust is funded when it only partially is.
What happens to an unfunded trust at death
Here's where the problem becomes concrete. If your trust was created primarily to help your family avoid New Jersey probate, that purpose only works for assets the trust actually owns. Probate applies to assets that are in your individual name when you die. Assets owned by your trust bypass probate because the trust owns them, not you.
If your trust isn't funded, your assets are still in your individual name. When you die, those assets still have to go through probate. The trust document exists, but it has nothing in it to govern.
Families often say to me, "but my attorney gave me a pour-over will." That's true, and the pour-over will is designed as a backstop. It says that any assets you didn't put into the trust during your lifetime should go into the trust at your death. Here's the catch: the pour-over will has to go through probate to work. So for every asset that reaches the trust through the pour-over will, probate still happens.
A pour-over will is a safety net, not a solution.
The common funding gaps
In my experience reviewing New Jersey estate plans, these are the assets most often left out of the trust:
Brokerage and investment accounts. Families fund their primary checking account but leave their larger investment accounts in individual name. These are often the biggest asset in the estate.
Secondary properties. The primary home gets funded; a vacation home, a rental property, or a second property for an adult child does not.
Property acquired after the trust was created. The family funds everything they own at the time the trust is drafted, then buys another property or opens another account years later and never retitles it. This is especially common for assets acquired more than five years after the original trust was signed.
Business interests. Business owners often never update their operating agreements or shareholder documents to transfer the business to the trust.
Out-of-state property. New Jersey families with property in Florida, Pennsylvania, or elsewhere often leave the out-of-state property outside the trust, which creates ancillary probate proceedings in multiple states.
Jointly held assets. Assets held jointly with right of survivorship don't need to go into the trust because they transfer automatically at death, but families often assume the opposite and either try to fund jointly held assets into the trust (which creates its own problems) or assume the trust protects jointly held assets (it doesn't).
How to check whether your trust is actually funded
Pull out your trust documents and compare them against your actual asset list. For each significant asset you own, ask:
- Whose name is on the title, deed, or account statement right now?
- If the name is yours individually, is this asset supposed to be in the trust?
- If so, when do you plan to retitle it?
For real estate, check the current deed. Your county clerk's office or online property records can tell you the exact name on the deed.
For financial accounts, log in or check a recent statement. The account holder's name is listed at the top. If it says only your personal name, the account is not in the trust.
For retirement accounts and life insurance, check your beneficiary designations rather than the account ownership. The question for these is whether the trust is named as beneficiary, not whether the trust owns the account.
If you find assets that should be in the trust but aren't, the fix is straightforward in principle: file the paperwork to retitle each one. In practice, it takes time and attention. Most families benefit from working with their attorney to complete the funding they thought was already done.
Why this happens so often
In fairness to clients and to the attorneys who draft these documents, trust funding falls between two sets of responsibilities. The attorney who drafts the trust typically produces a document and provides instructions for how to fund it. Actually completing the funding is on the client, and the client is often not an expert in retitling assets. Many families take the trust home with every intention of handling the funding steps, then life intervenes and the paperwork never gets filed.
If your trust was drafted some years ago and you're not sure whether it was fully funded, a review is worth doing now rather than discovering the gap after a death in the family, when the time to fix it has passed.
A trust is only as good as what's in it. If you went to the trouble of creating a trust, make sure it's actually doing the work you created it to do.
Your next step
Not sure if your revocable trust is fully funded? Download our Trust Funding Audit Checklist and walk through each asset category to see what has been retitled and what has not. If gaps turn up, the next step is a trust funding review with our firm. We identify what still needs to be retitled, handle the paperwork with you, and make sure the trust you created actually does what it was designed to do.
Recent posts
Explore more and stay updated on important legal topics affecting you and your loved ones.
What 20 Years of Elder Law Has Taught Me About Families — and What I Wish Every Family Knew Before the Crisis
Supported Decision-Making in New Jersey: A Rights-Preserving Alternative to Guardianship
Caregiver Burnout Is Real: How to Recognize It, Name It, and Find Your Way Through It
Get the Support You Deserve
Whether you’re planning ahead or facing an urgent legal matter, our team is here to help. Schedule a consultation or contact us today to get started.
